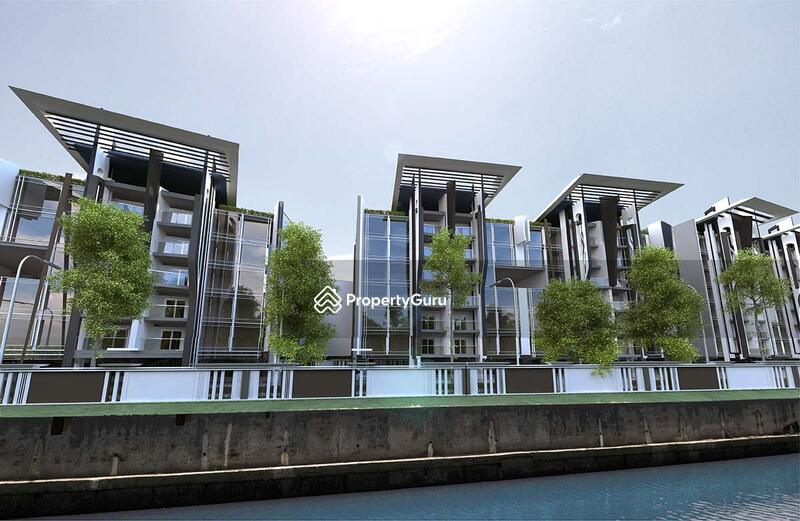
Your Complete Guide to Riverside Business Condominiums
Thinking about setting up an office or retail space by the water? A Riverside Business Condominium might be the sweet spot between a traditional lease and owning a standalone building. Below we’ll unpack what these properties are, why they’re gaining traction, and how you can pick the right one for your venture.
What Exactly Is a Business Condominium?
In plain terms, a business condo is a privately owned commercial unit that shares common infrastructure—like parking, security, and utilities—with neighboring units. Unlike a standard office lease, you hold title to the space, giving you control over renovations, branding, and long‑term financial planning. The “condominium” part comes from the shared‑ownership model, mirroring residential condos but tailored to business needs.
Why Riverside Locations Have an Edge
Riverside districts combine scenic appeal with growing economic activity. Here are a few reasons entrepreneurs gravitate toward these spots:
- Visibility. A riverfront façade draws foot traffic and adds prestige to client meetings.
- Community vibe. Many municipalities invest in parks, cafés, and cultural events that boost employee morale.
- Future appreciation. As cities redevelop waterfronts, property values often climb faster than inland equivalents.
That said, riverside parcels can also bring unique challenges—flood risk, stricter zoning, and sometimes higher insurance premiums. We’ll cover mitigation strategies later.
Key Benefits of Buying a Riverside Business Condo
Owning a unit gives you equity that a lease simply can’t match. Over time, the asset can become a financial cushion or even a source of rental income if you downsize. Additionally, you gain:
- Predictable costs. Monthly HOA fees usually cover maintenance of shared spaces, so you avoid surprise repair bills.
- Customization freedom. From interior layout to signage, you can tailor the space without landlord approval.
- Tax advantages. Property taxes and mortgage interest may be deductible as business expenses.
Things to Look Out For Before Signing
Even with the perks, due diligence is non‑negotiable. Keep an eye on these red flags:
- Floodplain designation. Verify the site’s elevation and whether the local government requires flood insurance.
- HOA financial health. Review the condominium’s reserve fund—insufficient reserves could lead to special assessments down the line.
- Zoning restrictions. Some riverside zones limit signage size or restrict certain types of businesses (e.g., heavy manufacturing).
Ask the seller or broker for recent meeting minutes of the HOA board; they often reveal ongoing disputes or upcoming capital projects.
Financing a Business Condominium
Because the property is commercial, lenders typically require a larger down payment—often 20‑30 %—and a shorter amortization period than residential loans. However, there are workarounds:
- SBA 504 loans. These can cover up to 40 % of the purchase price with favorable terms for small businesses.
- Seller financing. Some owners are open to a lease‑to‑own arrangement, which eases cash‑flow pressure.
- Bridge loans. If you’re renovating before leasing out, a short‑term bridge loan can fill the gap.
Shop around for a lender familiar with mixed‑use developments; they’ll better understand the nuances of a riverside condo.
Legal and Regulatory Checklist
Commercial real estate contracts are dense, so consider hiring an attorney who specializes in business properties. The following items should be on the agenda:
- Review the condominium declaration and bylaws—these dictate everything from operating hours to pet policies.
- Confirm that the property complies with the Americans with Disabilities Act (ADA) if you expect public foot traffic.
- Check for any pending litigation within the condo association; a lawsuit could affect future assessments.
Don’t skip the title search. Even a tiny easement can restrict future expansions or signage.
Design and Fit‑Out Tips for Riverside Spaces
Because the view is a major selling point, let it shine. Position workstations near windows, incorporate natural materials that echo the river’s palette, and consider outdoor terraces for client meetings. If you’re in a high‑traffic retail spot, large glass doors can invite passersby while still protecting against wind‑driven debris common near water bodies.
Case Study: A Boutique Law Firm’s Riverside Upgrade
When a mid‑size law firm moved into a 2,500‑sq‑ft condo on the east bank of the Riverwalk, they saw a 15 % rise in client referrals within six months. Their secret? Leveraging the river view for a sleek conference room, adding a small rooftop patio for informal consultations, and branding the entrance with subtle, water‑inspired graphics. The firm financed the purchase with an SBA 504 loan, keeping cash reserves for marketing and staff hiring.
Step‑by‑Step Roadmap to Secure Your Riverside Business Condo
1. Define your needs. Square footage, parking ratio, and proximity to transport hubs matter more than aesthetics alone.
2. Scout locations. Use city planning maps to identify flood‑plain boundaries and upcoming waterfront projects.
3. Engage a broker. Look for agents with a track record in commercial condos; they’ll have access to off‑market listings.
4. Run the numbers. Compare total monthly outlay (mortgage, HOA, insurance) against projected revenue.
5. Conduct due diligence. Inspect the building, review HOA docs, and verify zoning compliance.
6. Close the deal. Secure financing, sign the purchase agreement, and arrange for a smooth transition of utilities.
Frequently Asked Questions
Can I sublet part of my business condominium?
Usually yes, but you’ll need to check the association’s bylaws. Some condos prohibit subleasing to maintain a consistent tenant mix.
How does flood insurance differ for a riverside condo?
Standard commercial policies often exclude flood coverage, so you’ll need a separate National Flood Insurance Program (NFIP) policy or a private flood policy.
Are HOA fees taxable?
If the fees cover services that directly benefit your business—like security or common area maintenance—they’re generally deductible as operating expenses.
What’s the typical ROI for a waterfront commercial condo?
While exact figures vary, many owners report a 6‑8 % annual return when the property is fully leased, thanks to higher rental rates that waterfront locations command.