How to Grab the Best Toyota Car Deals and Financing Options
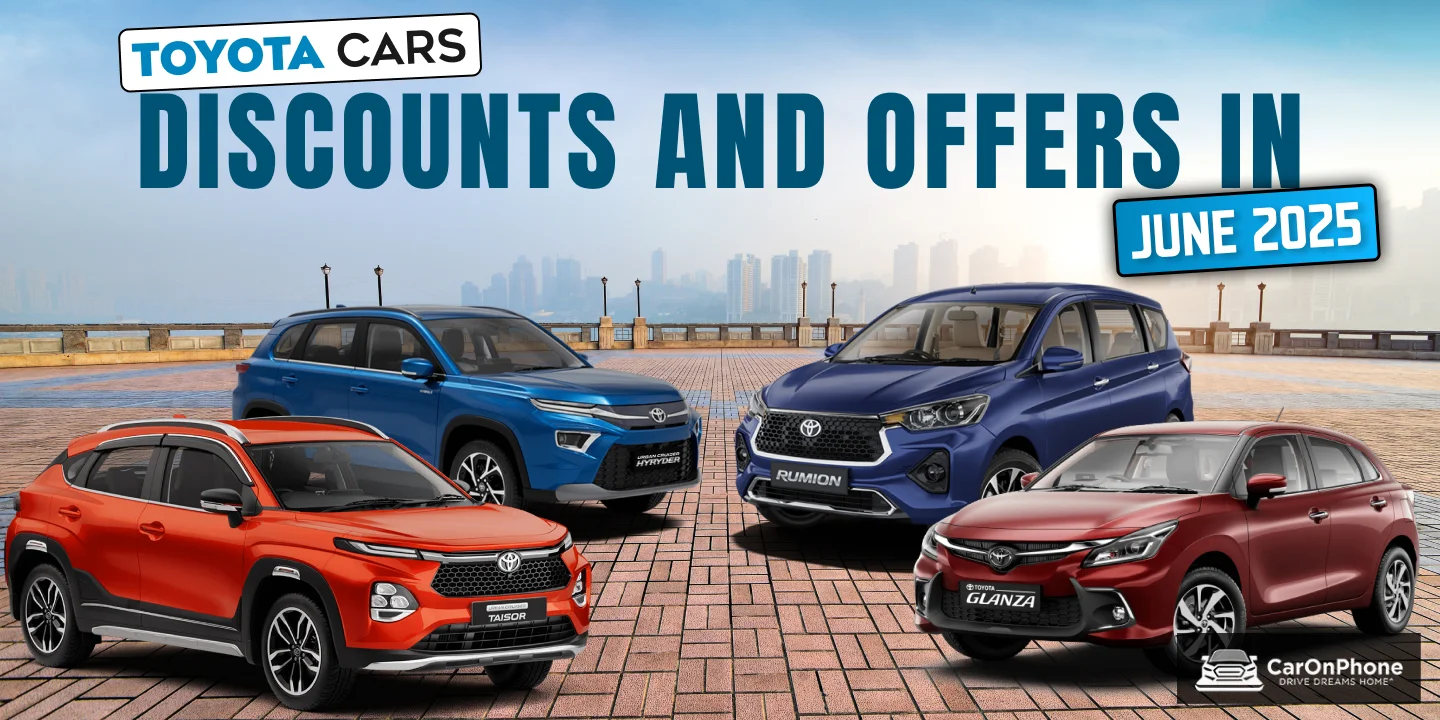
Buying a new Toyota can feel like navigating a maze of numbers, incentives, and paperwork. Whether you’re eyeing a compact hatchback or a family‑friendly SUV, understanding Toyota Car Deals Financing Options & Offers is the first step toward a smart purchase. This guide breaks down the key financing avenues, popular dealer incentives, and practical tips to help you lock in the best terms.
Types of Toyota Financing You’ll Encounter
Dealerships and Toyota’s own financing arm, Toyota Financial Services (TFS), offer several structured options:
- In‑House Financing (TFS): Direct loans with competitive rates, often featuring promotional APRs for qualified buyers.
- Lease Programs: Fixed monthly payments for 24–48 months, plus a final buyout if you decide to keep the car.
- Dealer‑Backed Credit: Partners with local banks to offer rates that may be lower than the national average.
Each pathway comes with its own eligibility criteria, so knowing which fits your credit profile and usage goals is crucial.
What Toyota Car Deals Are Really About
Toyota’s seasonal sales pushes usually include a mix of discounts, cashback rebates, and zero‑down offers. The core categories are:
- Cashback Incentives: A dollar‑for‑dollar rebate applied to the purchase price.
- Low APR Offers: Interest rates that can be 1–3 percentage points below market averages.
- Lease Specials: Reduced monthly payments and down‑payment waivers.
- Certified Pre‑Owned (CPO) Promotions: Extended warranties and low‑interest financing for used Toyota models.
Keep an eye on Toyota’s official website and local dealer flyers for the latest “as‑available” offers, as they can vary by region and inventory levels.
How to Qualify for the Best Deals
Credit score, down‑payment size, and term length all influence the final cost. Here’s how to maximize your chances:
- Check Your Credit Report: A score of 700 or higher often unlocks the lowest APRs.
- Save a Larger Down Payment: Putting 20% down can reduce the loan amount and monthly payment.
- Shorten the Loan Term: Choosing 36 or 48 months instead of 60 can lower interest, though payments will be higher.
- Consider a Pre‑Approved Loan: Borrowing from a bank before visiting the dealership can give you a stronger negotiating position.
Remember, the most attractive offer isn’t always the lowest monthly payment; total cost of ownership matters.
Negotiating the Price: Beyond the Sticker
Once you’ve narrowed your model choice, it’s time to talk numbers:
- Ask for the Invoice Price: The dealership’s cost, minus any incentives, is a solid benchmark.
- Leverage Competing Dealer Quotes: Use offers from nearby Toyota locations to sweeten the deal.
- Beware of “Add‑On” Fees: Optional accessories or extended warranties can inflate the price without adding real value.
- Clarify All Fees: Title, registration, and documentation charges should be itemized before you sign.
Keep the conversation focused on the vehicle’s value, not just the monthly payment.
Special Offers You Shouldn’t Miss
Dealerships often run limited‑time promotions that can change the equation entirely:
- New vs. Used: New Toyota models may have higher rebates, while CPO vehicles offer lower interest rates.
- Zero‑Down Deals: Some locations offer zero‑down financing for specific models, perfect for buyers with tight budgets.
- Student & Military Discounts: Verified students or active service members can receive additional rebates.
- Lease‑to‑Own Programs: Monthly payments are lower, and the final purchase price is predetermined.
Timing your visit at the end of a quarter or during holiday sales events can unlock these bonuses.
Closing the Deal: What to Check Before Signing
Final steps ensure you don’t miss hidden costs:
- Read the Loan Contract Carefully: Verify the APR, term, and total interest.
- Confirm Warranty Details: New cars come with a 3‑year/36‑month warranty; CPOs might have a 5‑year or 60‑kWh guarantee.
- Ask About Gap Insurance: Protects against loss if the car is totaled before the loan is paid off.
- Request a Detailed Receipt: All fees, taxes, and fees should be itemized.
Once you’re satisfied, you can walk away knowing the deal reflects the true value of the vehicle.
Frequently Asked Questions
Q: Can I combine a lease offer with a cashback incentive?
A: Many dealers allow simultaneous incentives, but the total discount may be capped. Verify the terms before acceptance.
Q: How does credit score affect Toyota financing rates?
A: Higher scores typically secure lower APRs, reducing the loan’s total cost.
Q: Are there hidden fees in the Toyota financing contract?
A: Look for title, registration, and documentation fees. These are usually disclosed upfront, but double‑check the final paperwork.
Q: Can I finance a used Toyota through TFS?
A: Yes, Toyota Financial Services offers special rates for certified pre‑owned vehicles.