How to Check If You’re Pre‑Approved for the OSCPNC Credit Card
What the OSCPNC Credit Card Actually Is
The OSCPNC credit card is a consumer‑focused product offered by the Ohio State Cooperative Public‑Network Credit Union. It’s marketed as a low‑interest, rewards‑oriented card for everyday purchases, and the issuer often runs pre‑approval campaigns to attract qualified members. Understanding the card’s basic features—such as a 0 % intro APR on balance transfers, cash‑back on groceries, and no annual fee—helps you decide whether a pre‑approval check is worth your time.
Why a Pre‑Approval Check Matters
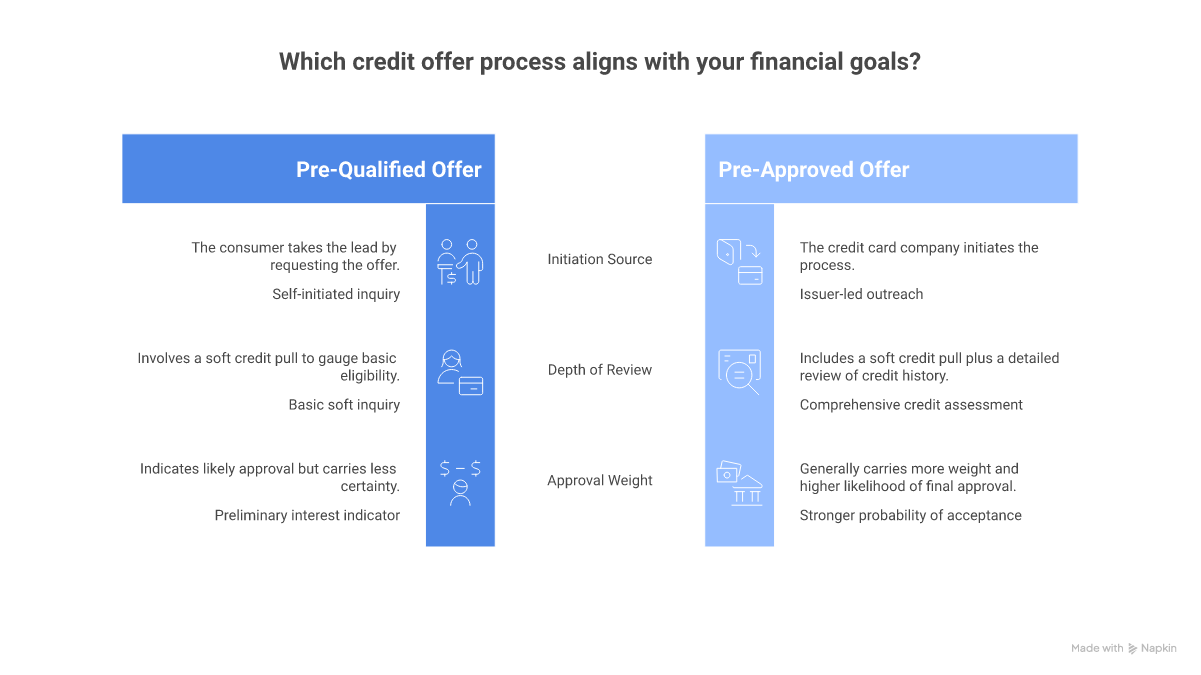
A pre‑approval is essentially a soft‑pull on your credit file that lets the lender gauge your eligibility without affecting your credit score. If you’re pre‑approved, the application process is usually smoother, and you may receive a higher credit limit or better promotional rates. It’s also a quick way to weed out cards that aren’t a fit before you commit to a full application.
How to See If You’re Pre‑Approved
There are three common ways to verify your pre‑approval status for the OSCPNC card:
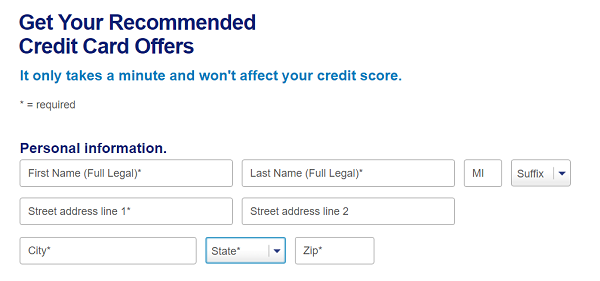
- Online pre‑approval portal. Visit the official OSCPNC website and look for the “Check Pre‑Approval” banner. You’ll be asked to enter basic personal details—name, address, date of birth, and the last four digits of your Social Security number. The system runs a soft inquiry and instantly tells you if you qualify.
- Mobile banking app. If you already have an account with OSCPNC, open the app, navigate to the “Credit Cards” section, and tap “Pre‑Approval Check.” The app uses the same soft‑pull method but also shows you tailored offers based on your existing relationship with the credit union.
- Phone or in‑branch inquiry. Call the member services line (1‑800‑OSCPNC) or drop by a local branch. A representative can run a pre‑approval check on the spot, answer any follow‑up questions, and even start the application while you’re there.
All three methods guarantee that your credit score won’t dip, because they avoid the hard inquiry that a full application triggers.
Eligibility Factors Lenders Look At
Even though a pre‑approval is soft, the underlying algorithm still checks key data points:
- Credit score range. Most OSCPNC pre‑approvals start at a FICO score of 680, though exceptions exist for long‑standing members with strong payment histories.
- Income verification. The system cross‑references reported income with the credit union’s internal records; a stable income stream improves your odds.
- Debt‑to‑income ratio. A lower ratio signals you can handle additional credit, so the pre‑approval engine favors applicants with modest existing balances.
- Existing relationship. Current OSCPNC members often receive preferential treatment, especially if they have a checking or savings account with the credit union.
If any of these factors fall short, you may still receive a pre‑approval but with a lower credit limit or a higher APR.
Next Steps After a Positive Pre‑Approval
Once the system confirms you’re pre‑approved, you’ll typically have a 30‑day window to submit a full application. Here’s what to expect:
- Gather documentation. Prepare proof of income (pay stubs or tax returns), a government‑issued ID, and your current address verification.
- Complete the full application. This step involves a hard credit pull, so be ready for a slight dip in your score.
- Review the offer. The lender will present the final APR, credit limit, and any introductory bonuses. Double‑check that the terms align with what was shown during pre‑approval.
- Activate the card. After approval, you’ll receive the card in the mail. Follow the activation instructions and set up online account access to start using rewards right away.
Common Pitfalls to Avoid
Even with a pre‑approval, a few missteps can derail your application:
- Multiple hard pulls. Applying for several cards in a short period can compound the impact on your score. Stick to one application at a time.
- Outdated information. If you’ve recently changed jobs or moved, update your OSCPNC profile before checking pre‑approval; otherwise, the system may flag inconsistencies.
- Ignoring the fine print. Some pre‑approvals include conditional clauses—like a minimum spending requirement to earn the cash‑back bonus. Read the details before you commit.
FAQ
Does checking pre‑approval affect my credit score?
No. OSCPNC uses a soft inquiry, which does not show up on your credit report and therefore leaves your score untouched.
How long does a pre‑approval remain valid?
Typically 30 days, though the exact window is disclosed in the pre‑approval notification. If you miss it, you can run another check.
Can I apply if I’m declined for pre‑approval?
Yes, you can still submit a full application. However, the chances of approval are lower, and the issuer may require additional documentation.
Is there any cost to check my pre‑approval status?
Checking is free. The only potential cost is the hard pull that occurs once you submit a full application.