How TF Bank Handles Debt Collection: A Step‑By‑Step Guide
Understanding TF Bank’s debt collection process can feel like decoding a secret language, especially when you’re already juggling bills. The good news is that the bank follows a fairly predictable set of steps, each designed to protect its interests while giving borrowers a chance to resolve outstanding balances. Knowing what to expect not only reduces anxiety but also equips you to respond effectively at every stage.
Why Understanding TF Bank’s Debt Collection Matters
When a loan or credit line falls behind schedule, the bank moves from friendly reminders to a more formal collection routine. Ignoring these signals can quickly lead to extra fees, a damaged credit score, and even legal action. By grasping the mechanics early, you can negotiate payment plans before the situation escalates, and you’ll avoid surprises that often come from miscommunication.
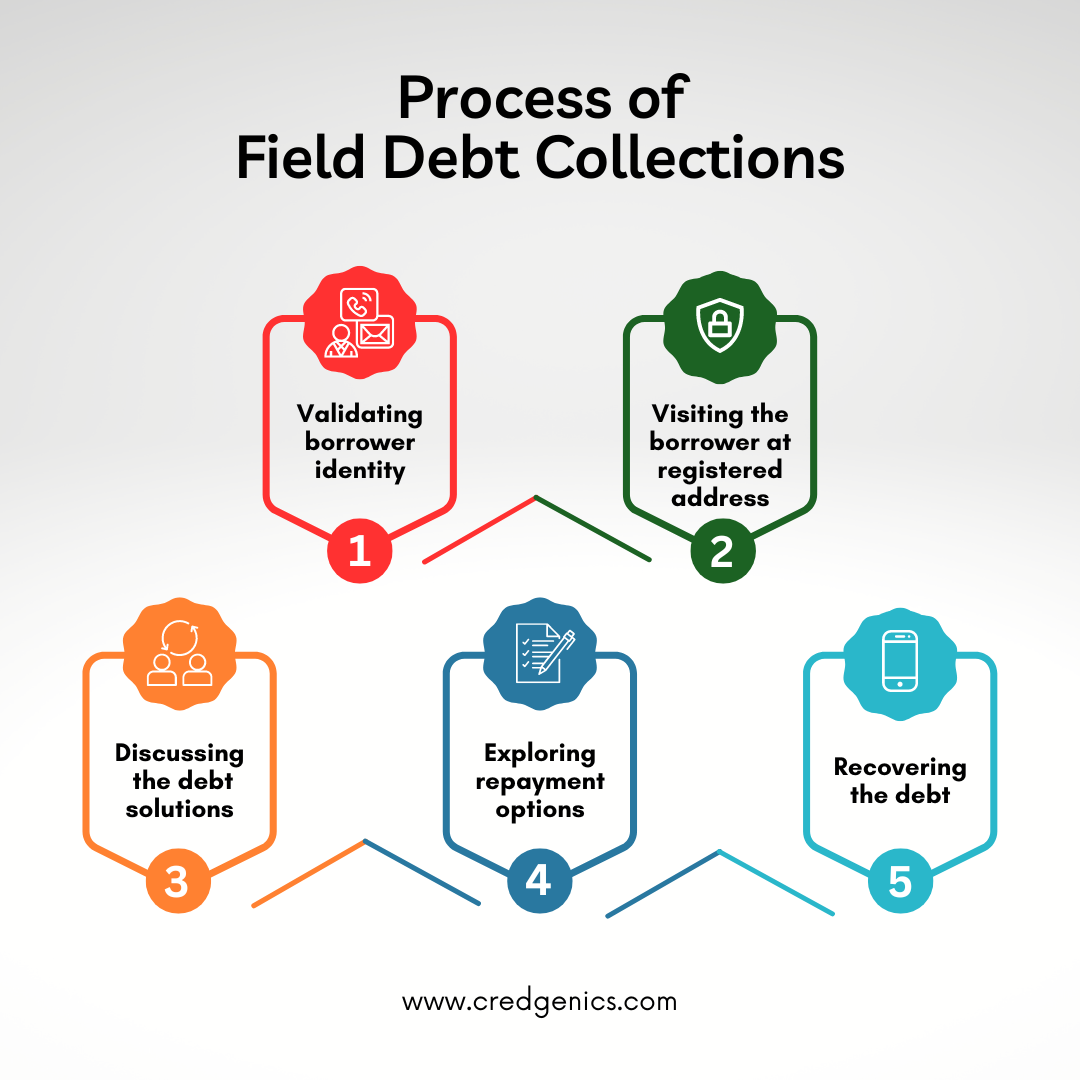
The Core Stages of TF Bank’s Debt Collection
1. Early Notification
Within a few days of a missed payment, the borrower typically receives an automated email or text reminding them of the due date. If the payment remains unpaid after a week, a more personalized phone call follows. At this point, the bank’s goal is simply to prompt action—not to threaten.
2. Verification and Validation
Should the debt linger, TF Bank sends a formal notice outlining the amount owed, any accrued interest, and the original loan terms. This document, often called a “validation letter,” gives the borrower a clear picture of the debt’s composition and offers a short window to dispute any errors.
3. Payment Arrangements
Most borrowers who contact the bank during the validation phase can negotiate a revised payment schedule. Options may include a temporary reduction in monthly installments, a lump‑sum settlement discount, or a short forbearance period. The bank typically records any agreement in writing to prevent future misunderstandings.
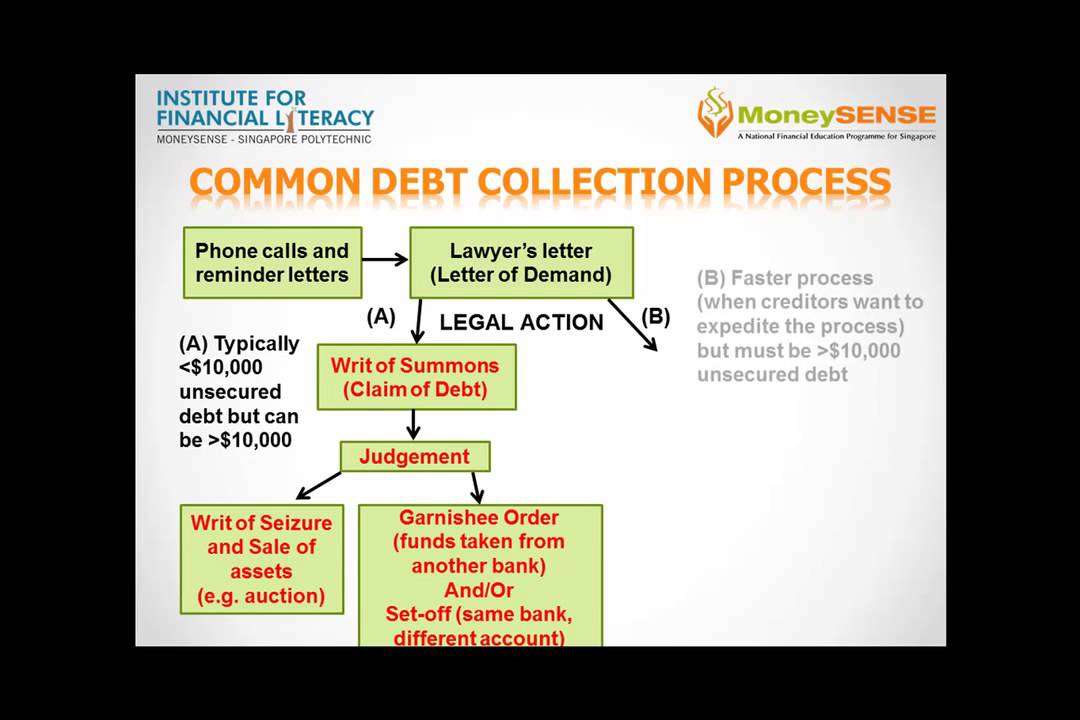
4. Legal Escalation
If the debt remains unresolved after multiple outreach attempts—usually after 90 days—the bank may refer the account to an external collection agency or initiate legal proceedings. This step triggers more serious consequences: credit report entries, potential wage garnishment, and, in rare cases, a court judgment.
Common Misconceptions About the Process
- “The bank will sue immediately.” In reality, litigation is a last resort, reserved for larger balances or cases where the borrower has repeatedly ignored all communication.
- “All collection calls are illegal.” TF Bank must follow the Fair Debt Collection Practices Act, which allows respectful, documented outreach. Aggressive or deceptive tactics would indeed be prohibited.
- “I can’t negotiate once a notice is sent.” Negotiation remains possible until a formal legal action is filed. Proactive communication often opens the door to flexible arrangements.
Tips for Borrowers to Navigate the System
- Act Quickly. Respond to the first reminder; a brief acknowledgment can halt the escalation clock.
- Keep Records. Save every email, letter, and note from phone calls. Documentation helps resolve disputes and proves you’re engaged.
- Ask for a Detailed Statement. Request a breakdown of principal, interest, and fees to ensure the amount matches your records.
- Explore Hardship Programs. TF Bank offers temporary relief options for borrowers facing unemployment, medical issues, or other crises.
- Consider Professional Advice. A credit counselor or attorney can review your situation and suggest the best negotiation strategy.
Frequently Asked Questions
What should I do if I believe the debt amount is incorrect?
Contact TF Bank’s collections department within the validation window and request a detailed audit. The bank is obligated to investigate and correct any errors before proceeding further.
Can I settle the debt for less than the full balance?
Yes, many borrowers negotiate a settlement that’s a percentage of the total owed, especially if they can pay a lump sum. The bank will document any settlement agreement in writing.
How long does the collection process usually take?
It varies, but most cases resolve within 60‑90 days if the borrower engages early. Legal escalation can extend the timeline to several months or longer.
Will a collection notice affect my credit score?
A single missed payment may cause a minor dip, but a formal collection entry can significantly lower your score and stay on your report for up to seven years.